
How to form an LLC: the basics
A limited liability company (LLC) is the structure most small businesses reach for when they outgrow operating as a sole proprietor or informal partnership. The appeal is straightforward: it separates the business from the person running it, at least on paper, without the extra paperwork and formality a corporation requires. That said, the exact steps, fees, and forms to form one vary significantly by state — this is a general overview of how the process works, not a substitute for checking your own state's specific requirements.
What an LLC actually does for you
Two things make an LLC worth the paperwork. First, liability protection: in most cases, if the business gets sued or can't pay a debt, the owner's personal assets — their house, personal bank account, car — are shielded from that liability. The business's debts stay the business's debts. Second, pass-through taxation: by default, an LLC doesn't pay corporate income tax itself. Profit and loss pass through to the owner's personal tax return, avoiding the double taxation a traditional corporation can face. Both of these are defaults, not guarantees — they depend on actually treating the LLC as a separate entity, which is a theme worth returning to below.
The general formation steps
Every state's process differs in the details, but most follow the same rough sequence:
- Choose a state to form in — usually the state where the business actually operates, since forming elsewhere (a popular move for Delaware or Wyoming) often just adds a second state's paperwork and fees if you're doing business somewhere else
- Pick a business name and check availability — most states require the name to be distinguishable from existing registered businesses and to include an LLC designator like "LLC" or "Limited Liability Company"
- File Articles of Organization (sometimes called a Certificate of Formation) with the state — this is the document that actually creates the LLC, typically filed with the Secretary of State's office along with a filing fee that ranges widely by state
- Get an Employer Identification Number (EIN) from the IRS — free, done directly through the IRS website, and needed to open a business bank account or hire employees even if the LLC has no employees yet
- Draft an operating agreement — not always legally required, but the document that actually governs how the business runs internally (more on why this matters below)
- Handle any required business licenses or permits — these depend on the industry and location, not the LLC filing itself, and are easy to overlook because they're not part of the state formation paperwork
Most states also require an ongoing step after formation — an annual report, a franchise tax, or a renewal fee — to keep the LLC in good standing. Skipping this is a common way an LLC quietly lapses without the owner realizing it until a lender or client asks for proof of good standing.
Single-member vs. multi-member LLCs
An LLC with one owner is a single-member LLC; one with two or more owners is a multi-member LLC. The formation paperwork is nearly identical either way, but the internal agreement looks different. A multi-member LLC needs to spell out how ownership percentages, profit splits, voting rights, and exit scenarios work between the owners — without that, state default rules fill the gap, and those defaults are rarely what a specific group of owners would have chosen for themselves.
A single-member LLC skips the ownership-split questions, but that doesn't make the operating agreement optional in practice. This is the part that surprises a lot of first-time owners.
Why a single-member LLC still needs an operating agreement
The liability protection an LLC provides isn't automatic just because the state approved the filing. Courts have "pierced the corporate veil" — the legal term for disregarding an LLC's liability shield and holding the owner personally responsible — in cases where a single-member LLC never documented any real separation between the business and the owner's personal finances. Commingled bank accounts, personal expenses paid directly from the business account, and no written record of how the business is actually supposed to operate all make it easier for a court to conclude the LLC was never treated as a separate entity in the first place — which undermines the entire point of forming one.
An operating agreement doesn't fix commingled bank accounts by itself, but it's a documented record that the owner set up formal rules for the business — how funds are handled, how the owner is compensated for their work, what happens if the business is sold or dissolved. Combined with actually keeping business and personal finances separate day to day, it's one of the more concrete things a single owner can point to if the LLC's separateness is ever challenged.
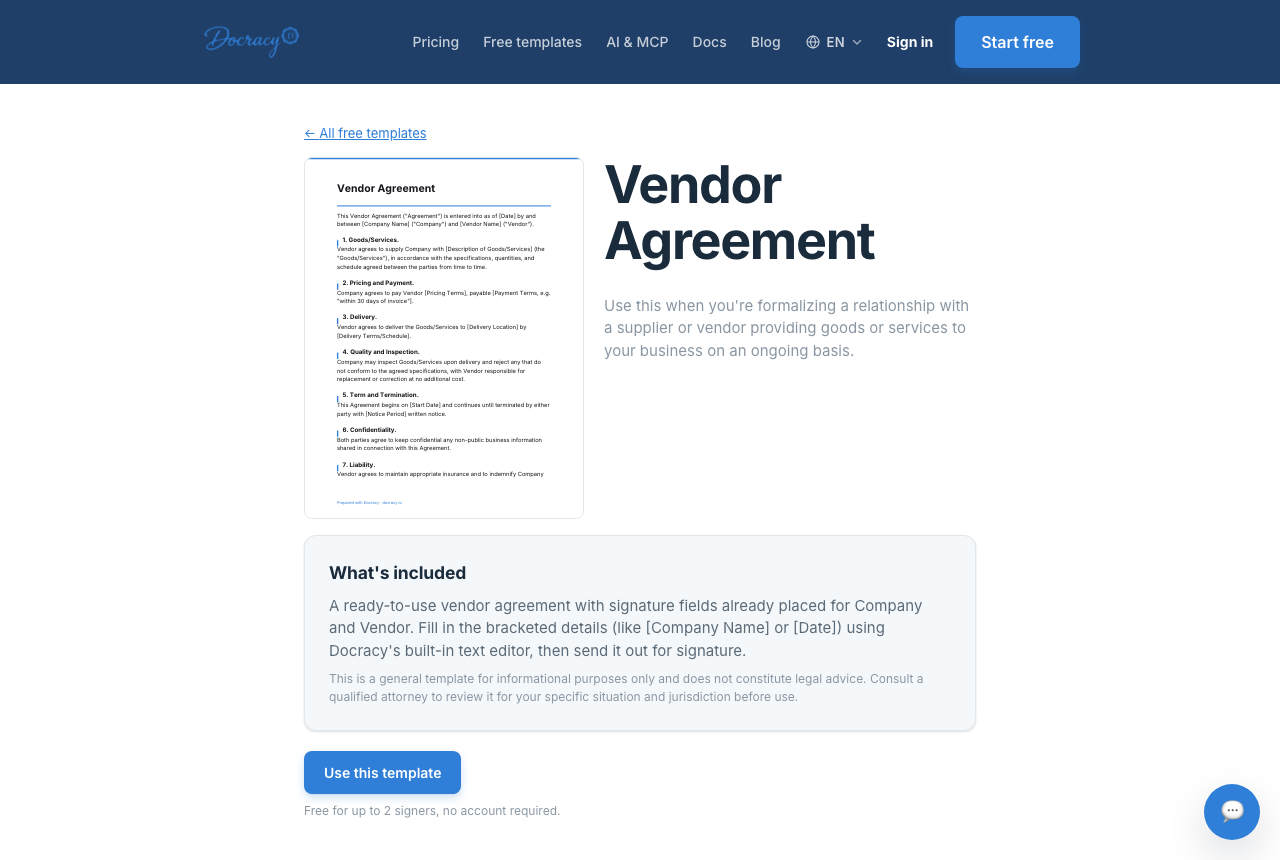
Free LLC operating agreement template
What formation doesn't cover
Filing Articles of Organization creates the LLC on paper, but it doesn't open a business bank account, get a resale certificate, register for state sales tax, or secure whatever industry-specific license the business needs to legally operate. It's easy to treat the state filing as the finish line and then discover months later that a required local permit was never applied for. Checking with the specific state and local government where the business operates is the only reliable way to get the full list — it genuinely varies too much to generalize.
Frequently asked questions
Do I need a lawyer to form an LLC?
Not for a straightforward single-owner or small-partner LLC in most states — many owners file directly through their Secretary of State's website. It's worth a lawyer's or accountant's time when ownership is complex, the business is raising outside investment, or the tax situation isn't simple pass-through.
How long does it take to form an LLC?
It varies by state, from same-day online approval to several weeks for a mailed filing. Some states also offer expedited processing for an extra fee if the timeline matters.
Can I convert a sole proprietorship into an LLC later?
Yes — this is a common path. Many businesses start as a sole proprietorship, then form an LLC once there's real revenue, a partner joining, or a specific liability concern worth addressing. There's no requirement to get the structure right on day one.
Does forming an LLC protect me from every kind of liability?
No. It generally protects personal assets from business debts and most lawsuits against the business, but it doesn't shield an owner from their own negligence, fraud, or a personally guaranteed loan. It also won't help if the business and personal finances were never actually kept separate.
Why teams start with Docracy
“Docracy is a great product that I have tested and am using. It is easy to use, has good tools, is always up to date, and implements new features. Highly recommended.”— DACH Advisory


Also: Compare e-sign pricing · Free mutual NDA template
No account required for up to 2 signers.